
Data Centers in the Arab Region: A $93 Billion Investment Boom Between Sovereign Ambitions and Operational Challenges
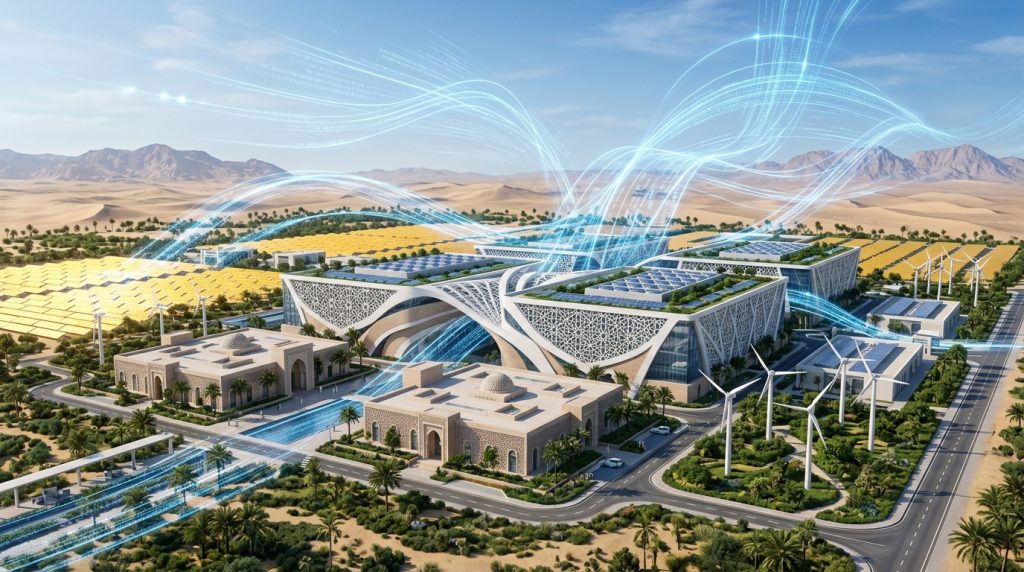
The Arab region is undergoing a radical transformation in its digital infrastructure, as data centers shift from mere technical facilities to strategic pillars of the knowledge economy and sovereign AI ambitions. This article, based on the latest international reports and specialized studies, reviews the quantitative and qualitative dimensions of the data center boom in the Middle East, and reveals a fundamental contradiction: while the region hosts projects worth more than $93 billion and attracts global technology giants, it faces unique logistical and regulatory challenges that may hinder this momentum. The article analyzes market structure, investment drivers, competition between local and global players, and the future outlook for this vital sector.
First: Market Size and Project Landscape — Figures Redrawing the Digital Investment Map
The Middle East is no longer merely a consumer of digital services; it has become a producer and exporter of computing capabilities. Data from GlobalData and MEED reveals that the six Gulf Cooperation Council countries currently host more than 174 active and planned data center projects, with a total value exceeding $93 billion.
1. Growth Indicators and Expansion Pathways
Mordor Intelligence estimates indicate that the Middle East data center market grew from $3.05 billion in 2025 to $3.52 billion in 2026, with projections of jumping to $7.19 billion by 2031, at a compound annual growth rate of 15.36%. The region’s data center colocation market is expected to grow by 28.5% annually to reach $4.9 billion in 2026, and then to about $11.1 billion by 2030, driven by AI demand and GPU-based workloads.
Regarding installed capacity, the Middle East’s installed capacity is expected to grow from about 3 GW in 2025 to about 6 GW by 2030, according to Rystad Energy estimates.
2. The Dominant Position of Tier 3 Facilities and the Shift Toward Tier 4
Tier 3 data centers accounted for 67.05% of market share in 2025, representing the optimal point between reliability and cost for multi-tenant applications. However, Tier 4 is growing at 16.55% annually, with projections that this segment will triple in size by the end of the decade, driven by AI training requirements, digital payments processing, and workloads of national importance.
Second: Drivers of the Boom — Between National Visions and Sovereign Ambitions
Analysts agree that the region’s data center boom is not coincidental but the product of intertwined structural factors:
1. Ambitious National Policies and “Sovereign Computing”
“Cloud-First Policies” in Saudi Arabia and the UAE form the cornerstone of this boom. These policies require ministries and state-owned companies to migrate their workloads to the cloud within specified timelines, creating a “guaranteed demand base” that protects developers from economic fluctuations. These directives also incorporate strict data sovereignty requirements, encouraging the establishment of sovereign cloud regions that generate premium returns.
National ambition programs such as Saudi Arabia’s “HUMAIN” program and the French-Emirati AI agreement top the list of initiatives generating guaranteed demand for GPU-dense computing halls.
2. Sovereign Investment and Overcoming Traditional Obstacles
The region’s sovereign wealth funds, such as Saudi Arabia’s Public Investment Fund (PIF) and the UAE’s G42, possess a unique ability to overcome obstacles that hinder traditional markets. Direct state investment removes “risk premiums” and compresses development timelines to 18–24 months instead of 3–6 years in crowded Western markets.
3. Geopolitical Advantage and Global Connectivity
The region benefits from its strategic location as a bridge between Europe and Asia, with the densification of subsea cables enhancing regional and global connectivity. This advantage makes the region a natural choice for providing computing capabilities to neighboring continents, especially given the computing capacity shortage in Europe.
Third: Unique Challenges — Between Regulatory Complexity and Operational Intricacies
Despite exceptional momentum, data centers in the region face unique operational and regulatory challenges that may hinder growth:
1. Complexities of Multi-Jurisdictional Regulatory Compliance
Regional countries impose varying data sovereignty and privacy regimes, increasing compliance complexity for international operators. This is compounded by the need to comply with international laws such as the General Data Protection Regulation (GDPR) when handling European citizens’ data, raising operational costs and requiring specialized legal teams.
2. Scarcity of Specialized Talent and Supply Chain Complexities
The regional market suffers from an acute shortage of certified data center engineers, increasing reliance on international recruitment and raising costs. The global supply chain is also under immense pressure with rising demand for critical equipment such as high-voltage transformers (average delivery time of 2.5 years), forcing developers to secure equipment before selecting sites—a reversal of the traditional “real estate first” model.
3. Heterogeneous Regional Digital Infrastructure
Some Arab countries suffer from gaps in communications infrastructure, limiting their attractiveness as locations for large data centers. Disparities in the development levels of subsea cables and terrestrial networks between countries create challenges in achieving the ultra-high-speed connectivity required by AI applications.
Fourth: Key Players — The Battle of Giants and a Multi-Party Competitive Landscape
The competitive landscape in the region is shaped by the interaction of three types of players:
1. Global Players (Hyperscalers)
Amazon, Google, Microsoft, and Huawei are investing in expanding their cloud regions in the Gulf, with mandatory partnerships with local operators to comply with data sovereignty regulations. These giants target the growing regional market, leveraging scale and global reach to offer competitive pricing.
2. National Champions
-
STC Group (Saudi Arabia): Targeting 1 GW through the center3 program, with plans to expand capabilities to include advanced cloud services.
-
Khazna (Mubadala – UAE): Leading efforts to build Tier 4 facilities in Abu Dhabi and Dubai.
-
e& Group (Etisalat – UAE): Developing integrated cloud regions with core telecommunications services.
-
G42 (UAE): Focusing on AI infrastructure and ultra-high-speed computing.
-
DataVolt: Developing a 1.5 GW AI factory in NEOM, representing a model for public-private partnerships.
3. New Players from the Energy Sector
Oil services companies such as Baker Hughes and Halliburton have begun entering the data center market, leveraging their expertise in regional infrastructure and mega-project management, giving them a competitive edge over newcomers from the pure technology sector.
Fifth: Future Outlook — Which Model Will Prevail?
Data centers in the Arab region stand at a decisive crossroads: either they become a global model for digital infrastructure supported by sovereign ambition, or they become hostage to infrastructure and regulatory challenges. The outlook appears promising, with the market expected to more than double in size by 2031, alongside a structural shift toward Tier 4 facilities and AI-capable fleets.
Key trends for the near future:
-
Gradual shift toward a bipolar market: Estimates indicate that the regional market will shift from UAE dominance to a bipolar structure with Saudi Arabia rising as the fastest-growing market, reflecting a broader geopolitical shift in the distribution of digital weight in the region.
-
Data center specialization: New facilities are expected to specialize in supporting specific applications such as AI, cloud gaming, and IoT, rather than the current general-purpose model.
-
Subsea cable integration: The region will strengthen its position as a global digital connectivity hub with continued expansion of subsea cable networks linking it to Europe, Asia, and Africa.
-
Regulatory maturation: The region is expected to witness gradual harmonization of data protection and sovereignty regulations, facilitating cross-border operations for international operators.
Sources and References
-
Mordor Intelligence (via Research and Markets). (2026). Middle East Data Center – Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026-2031).
-
GlobalData / MEED (via Research and Markets). (2026). The GCC Data Centre Projects Market 2026.
-
PayNXT360 (via Research and Markets). (2026). Africa & Middle East Data Center Colocation Market Size & Forecast – Q2 2026 Databook.
-
Rystad Energy (via Oil & Gas News). (2026). Data’s explosive growth forces reckoning across global energy markets.
-
Capacity Media. (2026). Why the Middle East is attracting major data centre investment.