
AI and Financial Auditing: From Sample Testing to Comprehensive Analysis
Financial and accounting auditing is undergoing a radical transformation thanks to artificial intelligence, moving from a model based on limited samples to comprehensive analysis of entire financial datasets. Recent research indicates that AI models can identify risks with high accuracy, achieving productivity gains of 30% to 40% according to client testimonials from leading companies in this field. AI adoption in financial reporting is expected to reach widespread levels in the coming years, with internal audit teams already using or planning to use generative AI to improve the quality and efficiency of their work. This article, based on academic research, institutional reports, and field applications, reviews the various dimensions of this transformation—from how AI works in auditing to regulatory and ethical challenges—while presenting applied models from leading companies.
First: The Shift from Samples to Comprehensive Analysis
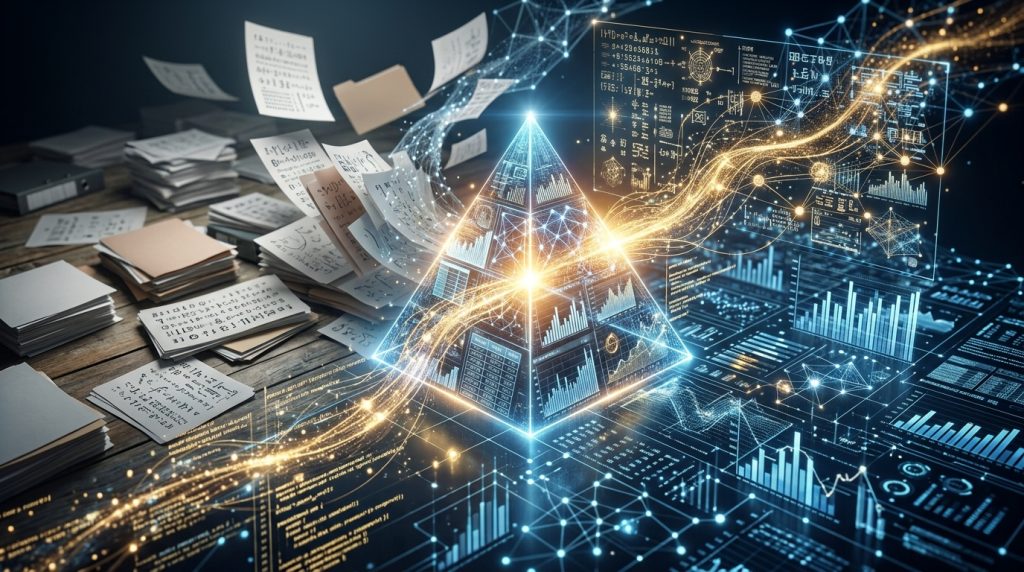
Traditional auditing methods have long relied on examining limited samples of financial transactions—a methodology that faces challenges in detecting anomalies or emerging risks in increasingly complex financial information environments. AI represents a qualitative leap through its ability to analyze entire datasets rather than samples, improving auditors’ ability to detect anomalies and allocate resources efficiently.
1. Core AI Technologies in Auditing
Digital financial auditing uses an integrated set of AI technologies, most notably:
-
Machine Learning: Systems that learn from data and make predictions or decisions without explicit programming, with the ability to update outputs over time. Used in risk assessment and detecting unusual patterns.
-
Natural Language Processing (NLP): Used to analyze unstructured data such as contracts, financial reports, and legal documents, extracting insights that previously required significant human effort.
-
Robotic Process Automation (RPA): Used to automate repetitive, rule-based tasks such as matching samples to supporting evidence and data collection, freeing auditors to focus on high-value analytical work.
-
Large Language Models (LLMs): Used to detect anomalies in journal entries, with studies showing these models outperform traditional rule-based approaches in detecting unusual transactions, while providing natural-language explanations that enhance transparency.
2. Measurable Results
Field studies demonstrate tangible effectiveness of AI in financial auditing:
-
Fieldguide’s platform, used by half of the largest U.S. accounting firms, has achieved productivity gains of 30% to 40%, with AI agents able to perform tasks typically outsourced to countries like India and the Philippines, leaving human auditors to interpret results and build trust relationships with clients.
-
A study on auditor-machine learning collaboration in going concern assessment showed that combining auditor judgment with machine learning capabilities achieves more accurate assessments than either method alone, as each errs in different cases, creating added value from integration.
-
In an academic study on using large language models for fraud detection in journal entries, the models outperformed traditional rule-based auditing methods (JETs) and significantly reduced false alerts, reducing the burden of manual re-auditing.
Second: Live Applied Models
1. Fieldguide — Agentic AI in Auditing
In February 2026, Fieldguide announced a $75 million funding round led by Goldman Sachs at a $700 million valuation. The platform uses AI agents to automate routine tasks such as testing revenue figures in financial statements, planning how to conduct the audit based on the client’s industry, and writing the procedures the audit team needs to follow. According to founder Jean Chang, a traditional 10-person audit team could perform the task with only three people within the next few years thanks to this automation, reducing burnout in the profession and accelerating junior auditors’ career paths.
2. Citi and IBM — A Unified AI-Powered Audit Platform
Citi partnered with IBM to design, build, and implement a unified AI-powered audit platform using IBM Watson Discovery, IBM Cloud Pak for Data, and IBM OpenPages. The platform automates document analysis, detects anomalies, and provides auditors with data-driven insights, reducing manual tasks and improving audit quality. The first use cases—including AI-powered control registration and NLP-based document analysis—saved hundreds of thousands of work hours.
3. BBVA — An AI Assistant for Internal Analysis
BBVA developed an AI assistant using ChatGPT Enterprise to support data analysis in internal auditing. The assistant guides auditors step by step in verifying source data, designing specific and complex analytical tests, and interpreting results. It also generates reproducible code in languages such as Python or SQL, with full documentation of constraints and the number of records used, giving auditors complete visibility into the analysis performed by the assistant. It is expected to increase productivity by about 10% in audits requiring intensive data analysis, while always leaving final judgment and conclusions to the human auditor.
4. AuditCopilot — Large Language Models for Fraud Detection
Researchers at the German Research Center for Artificial Intelligence (DFKI) developed a model called AuditCopilot that uses large language models to detect anomalies in journal entries. Results showed that LLMs outperform traditional rule-based JETs approaches and provide natural-language explanations that enhance transparency and understandability for non-technical auditors. The method was applied to real, anonymized accounting data and synthetic data, achieving competitive results compared to classical machine learning algorithms.
Third: AI Governance in Auditing — Regulatory and Ethical Challenges
With growing reliance on AI, regulatory and ethical challenges emerge that require precise governance to ensure transparency, fairness, and trust.
1. Evolving Regulatory Standards
The UK Financial Reporting Council (FRC) issued pioneering guidance in June 2025 on the ethical and effective use of AI in auditing. The guidance includes a case study on a coordinated approach to deploying AI tools and principles for documenting these tools in the audit file. Documentation requirements include: the tool’s function and suitability, how it was developed and related governance processes, available training materials, and the extent to which the tool’s behavior and decisions can be appropriately interpreted. The FRC stressed that the guidance is not mandatory but constitutes regulatory expectations for audit firms.
In July 2025, technological amendments to the Code of Ethics of the Institute of Chartered Accountants in England and Wales (ICAEW) came into force, including:
-
Professional competence: Requiring “ongoing awareness and understanding” of technology-related developments.
-
Confidentiality: Expanding the definition of confidential information to include any information not available to the public, with implications for using data in training generative AI models.
-
Ethical threats: A new section detailing threats arising from technology use, including self-interest and self-review threats.
2. Principles of AI Governance in Auditing
Researchers and practitioners converge on a set of core principles for AI governance in auditing:
-
Transparency and explainability: It is no longer sufficient to document only the outputs of an automated workflow; the rationale, data inputs, and model criteria that led to the decision must also be documented. An academic study showed that combining auditor judgment with machine learning capabilities achieves better results in going concern assessment, especially in contexts of economic uncertainty such as the COVID-19 pandemic.
-
Bias and fairness: Biases can creep into AI systems, requiring regular bias testing, use of fairness metrics, and independent auditing to detect and correct algorithmic bias.
-
Privacy and data confidentiality: Large language models raise concerns about the retention and retrievability of sensitive data. This requires encryption of data in transit and at rest, differential privacy techniques, and strict protocols for logging and reviewing queries.
Fourth: Conclusion and Future Outlook
Growing evidence shows that AI is redefining financial and accounting auditing at three interconnected levels:
-
Analysis level: Moving from sample testing to comprehensive analysis of entire datasets, enhancing risk detection accuracy and resource allocation efficiency.
-
Automation level: Automating routine tasks such as sample matching, evidence documentation, and data collection, freeing auditors to focus on high-value strategic analysis.
-
Governance level: Developing regulatory and ethical frameworks that ensure transparency, fairness, and accountability in AI use, with compliance requirements integrated into system design.
As for the future horizon, the industry is heading toward three main axes:
-
Integration of human judgment and machine capabilities: Evidence indicates that combining auditor judgment with AI capabilities achieves better results than either alone, especially in contexts requiring interpretation of information not easily codified, or under economic uncertainty.
-
Hybrid and explainable models: Combining the capabilities of complex models with built-in explainability engineering, integrating bias detection mechanisms and fairness assurance.
-
Sector-specific standards development: Growing pressure from regulators to unify requirements and explainable AI techniques in the financial sector, facilitating auditing and ensuring consistency.
The message is clear: the future of financial and accounting auditing will be built not only on the most accurate AI, but on the most transparent, responsible, and governance-integrated AI.
Sources and References
-
Goldman Sachs leads $75 million funding round for Fieldguide (Yahoo Finance, 2026)
-
Citi | IBM: AI-Powered Audit Platform (IBM Case Study, 2025)
-
Artificial intelligence and robotic process automation in auditing and accounting: a systematic literature review (ScienceDirect, 2025)
-
AICPA’s ‘Josi’ GenAI Research Tool (AICPA & CIMA, 2025)
-
How modern research tools are accelerating digital audit transformation (Wolters Kluwer, 2026)
-
How BBVA Uses an AI Assistant to Analyze Data in Internal Audit (BBVA, 2026)
-
Synergizing machine and human judgment: evidence from going concern assessment (ScienceDirect, 2026)
-
Artificial Intelligence in Accounting, Auditing and Finance (Springer Nature, 2025)
-
AuditCopilot: Leveraging LLMs for Fraud Detection in Double-Entry Bookkeeping (arXiv/DFKI, 2025)
-
Curvestone AI partners with The White Rose Finance Group (The Intermediary, 2025)
-
FRC and ICAEW Guidance on AI Use in the Accountancy Sector (Kingsley Napley, 2025)
-
Effective e-Business Accounting and Auditing Through AI Automatization (IGI Global, 2026)